
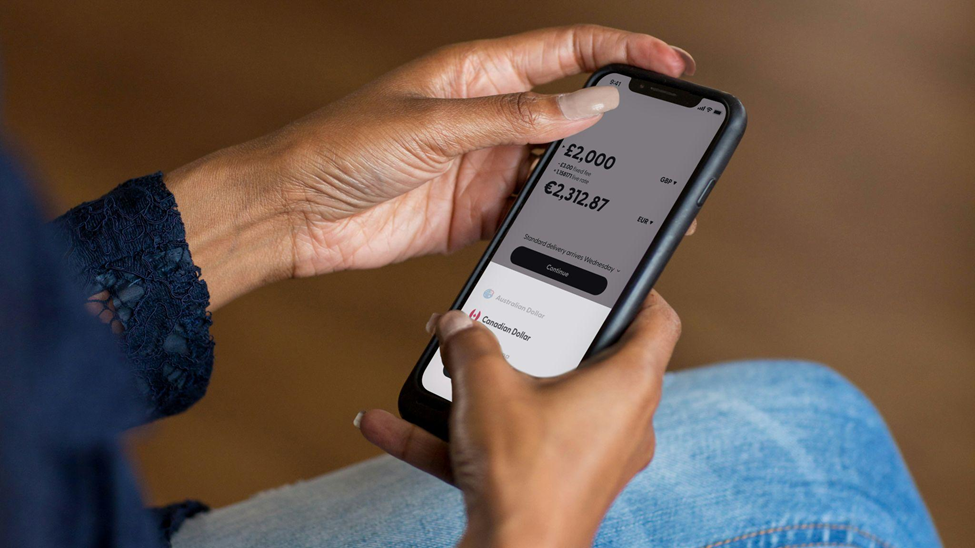
Money saving apps look similar on the store page, yet each one nudges you in a different direction. Some round up your UPI payments, others lock cash away for weeks, and a few just visualise where your salary went by the 20th of the month.
The right pick depends less on features and more on the way you actually behave with money. A tool that suits a salaried professional in Pune may frustrate a freelance designer in Kochi whose income arrives in irregular bursts.
Before installing anything, spend a quiet evening reading your last three months of bank statements. That short exercise reveals patterns you never notice in the moment, and it prevents you from choosing a fancy app that solves a problem you do not have. Readers who enjoy lighter breaks between spreadsheets sometimes unwind with something like a crazy time app where rules and limits are clear before the session begins, and then they return to the ledger with fresh eyes.
Start With Your Real Spending Personality
Apps assume you fit into one of a few money archetypes. Knowing which one describes you saves weeks of trial and error because the wrong category leads to wrong defaults and wrong reminders.
The Small Frequent Spender
If your statement shows dozens of tiny UPI transactions to tea stalls, cabs and quick commerce, you need an app that categorises automatically. Manual entry will collapse within a week. Look for tools that read SMS alerts and group merchants without asking you to tag every ten rupee coffee.
The Occasional Big Buyer
Some people spend calmly for weeks and then drop a large sum on electronics or travel. Round up apps do nothing for this pattern. What helps here is a goal-based app that lets you park money for planned purchases, so the big buy stops feeling like a shock to the account.
Match the Saving Mechanism to Your Willpower
Every app applies a different amount of friction between you and your cash. That friction is the actual product. If it is too soft, you drain the savings by Friday; if it is too harsh, you stop opening the app entirely.
Ask yourself honestly how often you have broken a fixed deposit early or cancelled a SIP after two months. The answer tells you whether you need gentle nudges or hard locks. Some helpful signals to weigh:
- Round up features work when your baseline spending is stable and you barely notice small deductions.
- Auto sweep to a linked savings account suits people who dislike separate wallets.
- Locked goal jars help those who confess to impulse withdrawals.
- Manual transfer apps only work if you already have the discipline, in which case a spreadsheet may serve just as well.
Pick the least aggressive mechanism that still moves the needle. Escalating friction later is easier than dialling it back once you resent the app.
Test for Two Weeks Before Committing
No review can replace two weeks of your own use. Install one app, not three, and give it a fair trial through a full pay cycle including at least one bill run and one weekend of leisure spending.
Track three simple things during the trial. Did you open the app without a reminder? Did the categorisation match how you actually think about the expense? Did the saving mechanism leave you comfortable or anxious? If any answer is a firm no, uninstall and try a different category of tool rather than a different brand in the same category.
Turning the Choice Into a Habit That Lasts
The app is only the wrapper around a habit. Once the shortlist becomes a single choice, protect the habit by keeping the notification tone soft, reviewing the dashboard on a fixed weekday, and resisting the urge to add more finance apps that fragment your attention. A single tool used weekly beats four tools opened once. Choose entertainment options for adults with the same clarity, set your own limits, and treat any leisure spend as a line item like any other in the monthly plan.
